
Have you ever asked yourself: If I fall sick tomorrow, who pays the bills? If I pass away suddenly, what happens to my family? For many Muslims, these questions are brushed aside until reality knocks. But in Islam, planning is not a luxury — it is part of our responsibility.
The Prophet ﷺ said: “It is sufficient sin for a man that he neglects those whom he is responsible to sustain.” (Sunan Abu Dawud 1692)
This is where the insurance question becomes more nuanced. Muslim scholars differ on conventional insurance. MUIS has acknowledged that disagreement, encouraged Muslims to choose arrangements they believe best fulfil Shariah requirements, and has allowed conventional insurance in specific situations of need where suitable takaful coverage is unavailable or inadequate. The practical question is therefore not simply whether every insurance product is halal or haram, but what the product contains, what need it serves and what alternatives are realistically available.
Young Professionals and New Parents
At the start of their careers, many young Muslims dream of marriage, children, and perhaps a first home. Yet life’s uncertainties do not wait.
- Practical goal: life insurance or savings plans that secure a child’s education and cover housing loans.
- Emotional hook: knowing your baby will be provided for, even if you are not there.
Think of it as Netflix for your family’s security — if you can auto-deduct for entertainment, you can surely auto-deduct for their well-being.
Middle Income Families in Their Prime
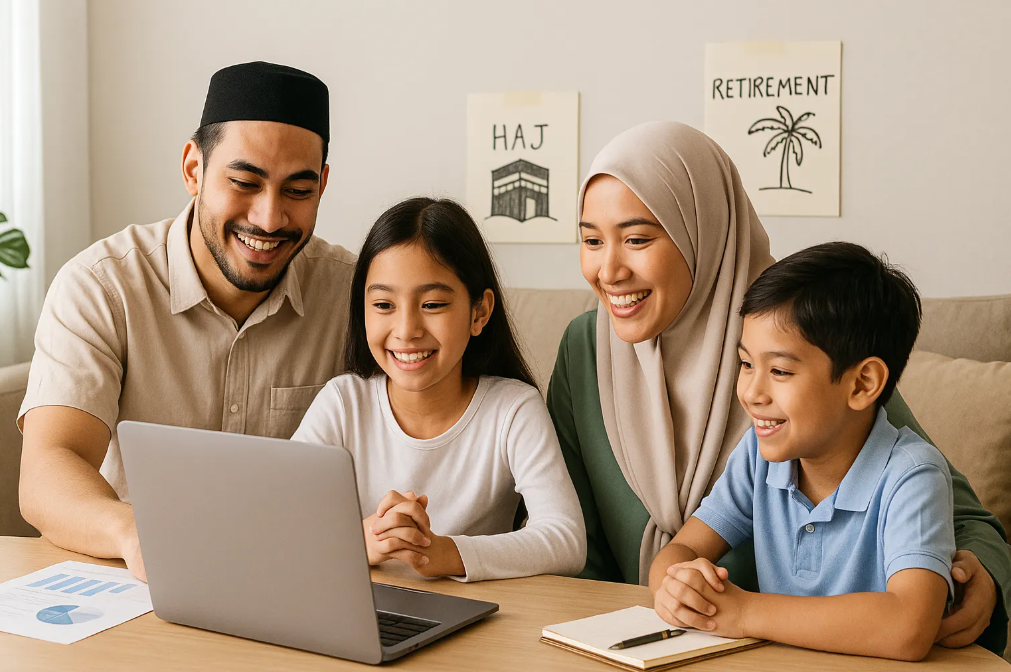
Families in their thirties and forties juggle housing loans, children’s tuition, and aging parents. A single illness can drain savings meant for Haj or retirement.
- Practical goal: critical illness riders and medical cover that prevent bill shock.
- Emotional hook: peace of mind to focus on ibadah, not invoices.
Insurance should not be sold through religious emotion or a Quran verse that is not specifically about insurance. The practical question is whether the cover meets a genuine need, whether a suitable takaful option exists, what the policy costs, and what religious view the person follows.
Seniors Preparing for Retirement and Haj
For seniors, the dream is often twofold — retire with dignity and fulfil the Haj. Yet health risks rise with age.
- Practical goal: savings insurance or endowment plans dedicated to Haj packages or sustaining retirement.
- Emotional hook: ensuring your children are not burdened, while you focus on worship.
Insurance nominations can also form part of legacy planning. MUIS treats revocable insurance nominations as a contemporary form of hibah. A payout can be directed to eligible beneficiaries or charitable purposes according to the relevant nomination and estate planning rules, but a one time donation should not automatically be labelled sadaqah jariyah unless it genuinely creates an ongoing benefit.
Read MUIS guidance on revocable insurance nomination
Students and First-Job Starters
University and polytechnic graduates may see insurance as “adult stuff.” Yet one accident or illness can wipe out their modest savings.
- Practical goal: affordable starter plans that cover hospital bills.
- Emotional hook: securing the future so early dreams are not derailed.
This stage is less about luxury and more about discipline — building the habit of protecting your rizq from the start.
So, Is Insurance Halal or Necessity?
There is no single sentence that settles every insurance product. MUIS has encouraged Islamic insurance or takaful where suitable, while also recognising scholarly views that allow conventional insurance in particular circumstances of need. Muslims should examine the actual policy, the purpose of the cover, available alternatives and the scholarly view they are persuaded by.
Using insurance does not by itself prove stronger or weaker faith. It is a financial contract that should be assessed by its structure, purpose, alternatives, cost and the scholarly guidance a Muslim follows.
Closing Thoughts
Muslims do not need to treat every insurance product as automatically identical. Takaful may be preferred where it meets the need, while MUIS has recognised circumstances in which conventional insurance can be used. Read the actual policy rather than relying on a label.
If you want to explore further, speak to advisers who understand both financial planning and Islamic principles. This is where insurers offering Sharia-compliant options — and those adapting to necessity rules — can make a real difference.
Advertiser opportunity: Rethinking Islam welcomes suitable financial professionals who can contribute transparent, responsible guidance for Muslim families in Singapore.
The useful conclusion is simpler: protect genuine needs, understand what you are paying for, compare alternatives, and keep religious claims separate from sales language.
Advertiser Opportunity
Rethinking Islam welcomes suitable Singapore financial professionals who can contribute transparent educational information about protection, takaful, insurance and family financial planning.
This space does not represent a current financial adviser or insurer.
Disclosure: This article currently contains an advertiser opportunity and does not represent a paid financial sponsor.
Disclaimer: This sponsored section is for informational purposes only and does not replace independent legal or religious advice. Rethinking Islam reviews content for accuracy at the time of publishing. Services, fees, and availability may change. Always consult qualified professionals for your specific situation.
