
Introduction
Let’s be honest. Many Muslims in Singapore treat investing like that exercise bike in the living room, bought with good intentions, parked in the corner, and gathering dust. Meanwhile, bills, school fees, and retirement worry keep piling up. Why are we falling behind? The answer is not that Islam discourages wealth, but that we often confuse what is halal, what is haram, and what is simply a missed opportunity.
Trade is Halal, Riba Is Not
The Quran states that Allah has permitted trade and forbidden riba (Quran 2:275). That gives Muslims room to invest, but it does not mean every investment is automatically permissible. The asset, business activity, contract structure and source of returns still matter.
Case in point: CPF interest. MUIS has ruled that interest credited by the CPF Board to a member’s account is not riba because it is not a gain arising from a loan, debt or pawn transaction. The Fatwa Committee describes it instead as a gift without conditions. You can read the ruling here: MUIS Fatwa on Interest in CPF Account.
Stories From Our Tradition
Islamic history is full of reminders that managing wealth wisely is not greed, it is foresight.
- Prophet Yusuf (peace be upon him) saved Egypt from famine by planning storage and distribution of grain strategically (Quran 12). That’s investment with vision — not hoarding, but anticipating the future.
- The Prophet ﷺ once said: “It is better to leave your inheritors wealthy than to leave them poor, begging others.” (Bukhari 2742, sunnah.com link)
The hadith supports responsible provision for heirs. It does not require every Muslim to invest, and it does not guarantee barakah from any particular financial product.
Why Muslims Are Falling Behind
Here comes the teasing part — because sometimes we need to laugh at ourselves before we fix things.
- CPF interest: MUIS has ruled that interest credited by CPF is not riba because it does not arise from a loan or debt transaction.
- Insurance: Muslim scholars differ on conventional insurance. Takaful may be preferred where suitable, while particular circumstances can require a more detailed religious assessment.
- Crypto: A digital asset should not be treated as halal merely because it is popular. The structure, use, risks and scholarly screening still matter.
The bigger issue is not whether Muslims as a group are “falling behind”. That requires reliable, current evidence. The practical concern is simpler: many people hesitate to invest because they are unsure how to distinguish lawful investing from riba, excessive uncertainty and prohibited business activity.
That uncertainty is a reason to improve financial literacy, not a reason to make sweeping claims about the community.
Where to Start Confidently
If you want to begin investing more carefully, start with the basics:
- Educate yourself. Read MUIS fatwas, follow AAOIFI standards, and use Shariah stock-screening tools.
- Understand diversification. Shariah screened equities, sukuk and some funds may provide different types of exposure, but availability, risk and screening standards vary. Takaful is a protection product, not automatically an investment substitute.
- Think long term. Prophet Yusuf’s plan worked because he thought seven years ahead — not seven days.
When it comes to financial planning, every recommendation should be understood before it is accepted. Mohamad Hans Edzra is listed in AIA’s 2026 agency directory under MFA Group. Readers should still ask any adviser to explain the product structure, fees, risks and the basis for describing an investment as Shariah compliant.
Mohamad Hans Edzra is listed in the AIA Agency Recognition 2026 directory under MFA Group. His public professional profile discusses Islamic finance and Shariah compliant planning. Readers should still ask for the current product documents, fees, risks and the specific basis for any Shariah compliant description before acting.
MAS Guidelines on Islamic Finance
For the regulatory framework and guidance on Islamic banking and finance in Singapore, refer to the official MAS publication:
MAS — Guidelines on the Application of Banking Regulations to Islamic Banking
Call to Action
Start with knowledge before products. If you use a financial adviser, verify the adviser’s regulated status, understand how the person is paid, ask what alternatives were considered, and request the evidence behind any Shariah compliant claim.
Mohamad Hans Edzra — Shariah Compliant Financial Consultant in Singapore
Mohamad Hans Edzra is listed in AIA’s 2026 agency directory under MFA Group. His public professional profile records MDRT recognition through 2025. Readers considering financial products should review the current product documents and ask how any Shariah screening or advisory process is applied before making a decision.
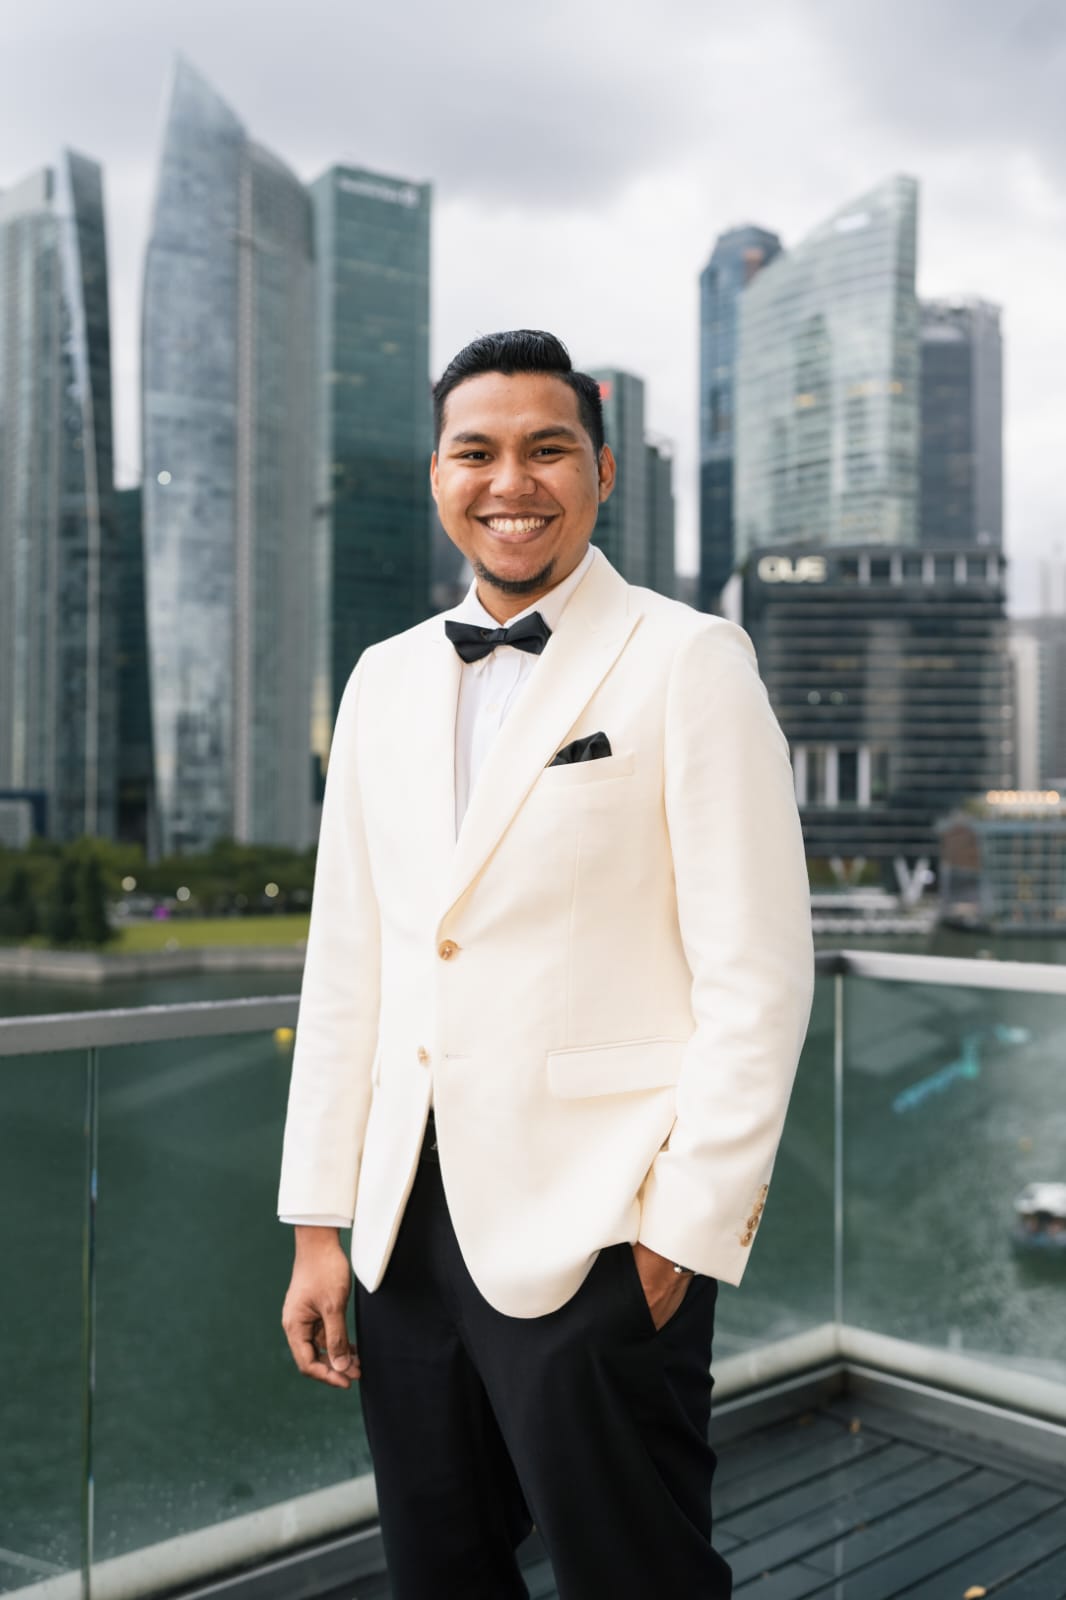
Mohamad Hans Edzra, Financial Consultant in Singapore
Listed in the AIA Agency Recognition 2026 directory under MFA Group.
Public professional materials describe an interest in Islamic finance and Shariah compliant financial planning. Readers should verify current qualifications, product documents and the Shariah basis of any recommended solution directly before making a financial decision.
Message on WhatsApp
Read More
- Loans in Singapore: When Necessity Knocks, What Do We Do?
- Discover Dubai Where Modern Muslim Travel Meets Smart Property Investment
